Get Out of Debt Fast: Real-World Step-by-Step Plan
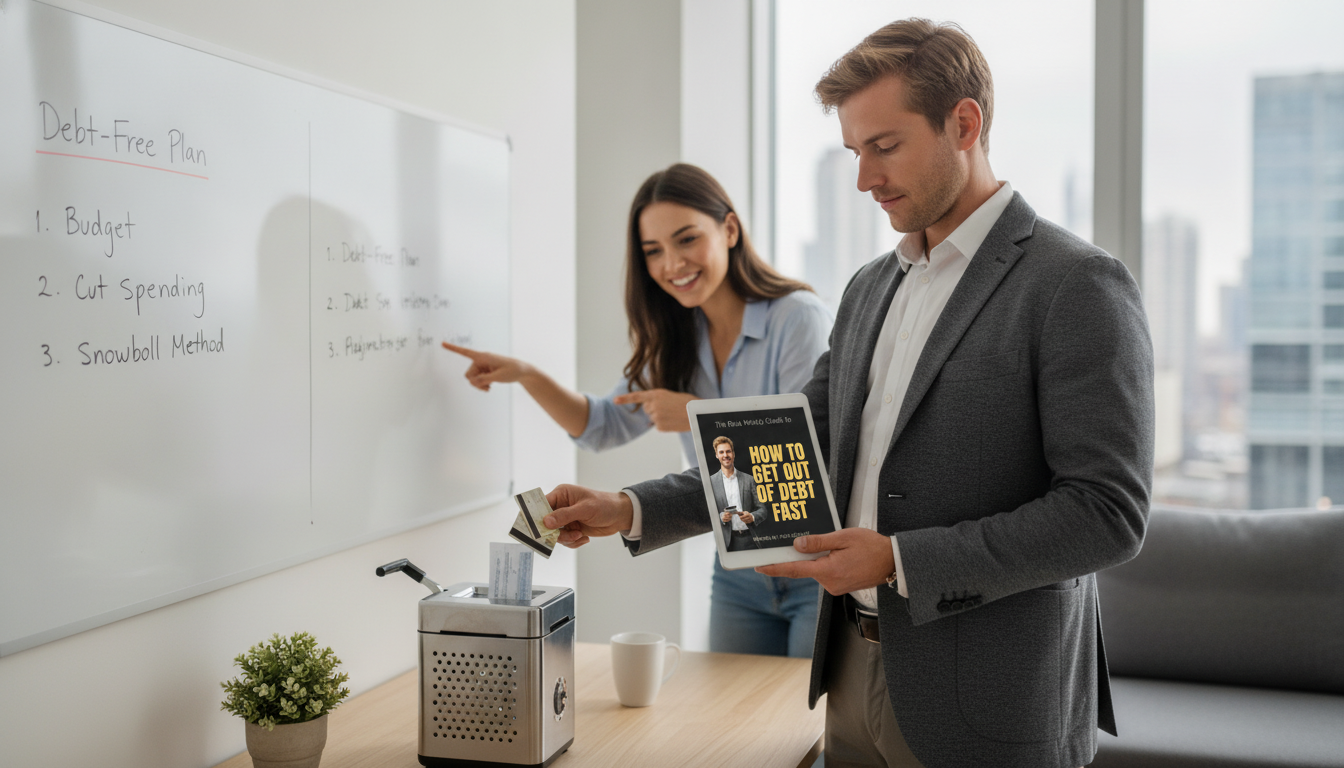
Debt payoff feels overwhelming when bills, interest, and day-to-day expenses collide. A faster path usually comes from a clear plan, simple rules, and a system that makes progress visible. Below is a practical, real-life sequence to organize what you owe, create cash flow, pick a payoff method, and stay consistent—without trying to do everything at once.
Start with a clear snapshot of every debt
Speed starts with clarity. Before choosing a “strategy,” get every debt on one list so there’s no guessing, double-paying, or missed due date.
- List each debt with: balance, interest rate (APR), minimum payment, due date, and lender.
- Separate secured vs. unsecured debts to understand risk and prioritize stability (rent/mortgage, utilities, transportation).
- Pull recent statements or use the lender portal to confirm APR and minimums; small inaccuracies can derail the plan.
- Pick one “system of record” (spreadsheet, notes app, or budgeting tool) and update it weekly.
| Debt | Balance | APR | Minimum | Due Date | Payoff Priority |
|---|---|---|---|---|---|
| Credit Card A | $3,200 | 24.99% | $95 | 15th | High |
| Car Loan | $9,800 | 6.10% | $275 | 1st | Medium |
| Student Loan | $14,500 | 4.50% | $165 | 20th | Low/Medium |
Create breathing room: stabilize cash flow in 7–14 days
Trying to “crush debt” while your month is unstable usually leads to new charges, overdrafts, and stress spending. The fastest plan is often the one that prevents backtracking.
- Cover the basics first: housing, utilities, food, and transportation; a stable month prevents new debt.
- Set a bare-bones spending plan for one month: essentials + minimum debt payments only.
- Pause or reduce non-essential subscriptions, dining out, and impulse spending; redirect the difference to debt.
- If cash is tight, negotiate: ask lenders about hardship options, due date changes, or temporary rate reductions.
- Build a small starter buffer (even $300–$1,000) to avoid relying on credit cards for surprises.
If collectors are involved or you’re unsure of your rights, the CFPB’s consumer guidance is a solid place to start: Consumer Financial Protection Bureau — Debt collection and credit topics.
Choose a payoff method that matches motivation and math
The “best” payoff method is the one that gets executed every payday. Pick a method, commit for 30 days, then adjust if needed.
- Debt avalanche: pay minimums on all debts and put extra money toward the highest APR first; typically minimizes interest cost.
- Debt snowball: pay minimums on all debts and put extra toward the smallest balance first; often boosts momentum and consistency.
- If sticking with the plan is the main challenge, the method that keeps payments consistent usually wins.
- Automate minimum payments to avoid late fees, then schedule the extra payment to the target debt after each paycheck.
For general consumer steps and pitfalls to avoid, the FTC offers straightforward guidance: Federal Trade Commission (FTC) — Getting Out of Debt.
Find extra money without burning out
Big changes are great—but small, repeatable wins are what make debt drop month after month. Aim for a mix of expense cuts and temporary income so you don’t feel deprived.
- Cut friction costs: insurance shopping, renegotiating internet/phone, lowering energy use, meal planning, and using a strict grocery list.
- Sell unused items and apply proceeds immediately to the target debt (avoid letting cash “sit” and disappear).
- Add temporary income: overtime, freelancing, weekend shifts, or a short-term gig aimed at a specific payoff milestone.
- Redirect “found money” (refunds, bonuses, cash gifts) to debt by default—decide any portion for fun spending in advance.
A helpful mental shift: treat extra payments like a “bill” you owe your future self. When the extra payment is scheduled, it’s harder to negotiate it away in the moment.
Stop the backslide: simple rules that protect progress
Debt payoff isn’t only math—behavior matters. Put guardrails in place so one tough week doesn’t undo a month of progress.
If you’re looking for a mindset reset to reduce self-sabotage and stick with your plan, consider Break Free: Stop Self-Sabotage Today.
Make the plan visible: milestones, tracking, and quick adjustments
To keep your self-talk focused during the grind, a quick daily prompt can help: Speak Success: Your Power Words Action Checklist.
A structured option: step-by-step eBook for a guided payoff plan
- For readers who prefer a clear checklist and an organized sequence of actions, a dedicated guide can reduce decision fatigue.
- The Real-World Guide to How to Get out of Debt Fast: Your Step-by-Step eBook to Financial Freedom focuses on practical, actionable steps designed to turn scattered efforts into a consistent routine.
- Best fit: anyone who wants a ready-to-follow framework for organizing debts, choosing a payoff approach, and staying on track week to week.
FAQ
Is it better to pay off the smallest debt first or the highest interest rate first?
Paying the highest interest rate first (avalanche) usually saves the most money, while paying the smallest balance first (snowball) often builds faster motivation. Choose the approach you’ll follow consistently—steady execution beats a “perfect” plan that stalls.
How much should be saved before paying extra on debt?
A small starter emergency buffer (often $300–$1,000) helps prevent new credit card charges when surprises happen. After that, prioritize extra payments on high-interest debt while gradually building savings alongside your payoff plan.
What if minimum payments are too high to manage?
Contact lenders to ask about hardship programs, temporary rate reductions, or due-date changes, and reduce expenses or increase income short-term to stabilize. Consider consolidation only if it clearly lowers total cost and doesn’t increase risk or extend the debt unnecessarily.

Leave a comment