Family Money Meetings: Save More Together Without Stress
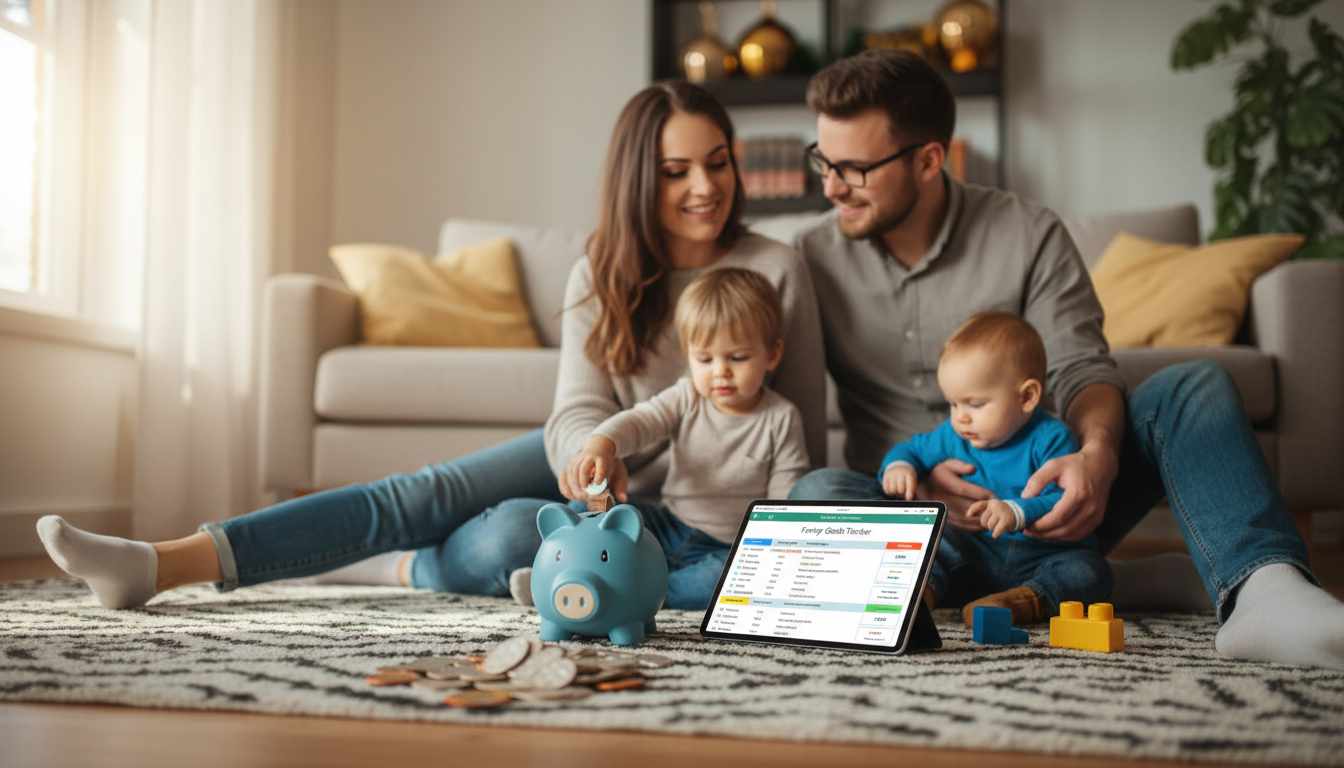
Family First, Finances Next: A Real-Life Guide to Saving Money Together
Saving as a family works best when money decisions feel shared, simple, and tied to goals everyone cares about. The goal isn’t perfection—it’s a routine everyone can follow without constant stress or blame. With short money check-ins, a clear spending plan, and one visible goal, everyday choices start stacking into real progress.
Start With a 20-Minute Family Money Meeting
A short, consistent meeting beats a once-in-a-while “big talk.” Pick a time that’s realistic (Sunday evening, Wednesday after dinner, or the first and third Saturday). Keep it to 20 minutes so it stays doable even during busy weeks.
- Set ground rules: no shaming, focus on solutions, and separate “needs” from “nice-to-haves.”
- Use a shared scoreboard: cash on hand, bills due, and current goal progress.
- Assign small roles: bill checker, grocery tracker, and goal captain so everyone participates.
- Keep decisions tiny: one adjustment, one next step, then done.
| Time | Topic | What to Decide |
|---|---|---|
| 3 min | Quick wins | One thing that went well and one challenge to solve |
| 7 min | Bills & calendar | What’s due before the next meeting and who pays it |
| 7 min | Spending plan | Limits for groceries, fuel, eating out, and kid activities |
| 3 min | Goal check-in | Add to savings, adjust timeline, or plan next step |
If it helps to stay calm and clear during the meeting, a simple script can keep everyone aligned. The Speak Success: Your Power Words Action Checklist can be used to set a “team language” tone—especially useful when the topic is emotionally charged.
Build a Family Budget That Matches Real Life
A workable budget is less about strictness and more about making sure the “known stuff” gets handled before money disappears into the week. Build it in this order so it reflects reality.
For trusted budgeting basics and worksheets, the Consumer Financial Protection Bureau (CFPB) budgeting resources are a solid place to cross-check your approach.
Budget Categories to Include (Even If Amounts Start Small)
| Category | Examples | Why It Matters |
|---|---|---|
| Fixed bills | Rent/mortgage, internet, insurance | Prevents missed payments and late fees |
| Daily living | Groceries, gas, toiletries | Controls the categories that drift the most |
| Sinking funds | Holidays, school fees, medical copays | Turns big spikes into predictable monthly amounts |
| Goals | Emergency fund, vacation, down payment | Creates visible progress and shared motivation |
| Flex/fun | Family treat, hobbies | Reduces burnout and all-or-nothing thinking |
Choose One Shared Goal and Make It Visible
Examples of Family Goals and First Steps
| Goal | Starter Target | First 2 Actions |
|---|---|---|
| Emergency fund | $500 | Automate a small weekly transfer; cut one subscription |
| Debt payoff | One card/loan | List balances; choose a payoff method and monthly amount |
| Family trip | $300 | Open a separate savings bucket; set a weekly cash-back sweep |
| School expenses | $200 | Price supplies early; set aside a monthly sinking fund amount |
To keep goal tracking, bills, and weekly check-ins in one place, use a single family planner system. The Family First, Finances Next digital family budget planner is designed for quick updates—so the plan stays visible without turning into a second job.
Make Saving a Team Habit (Not a Willpower Battle)
For practical, family-friendly money lessons and habit-building tools, the FDIC Money Smart program is a helpful reference.
Two small tools that make the routine easier
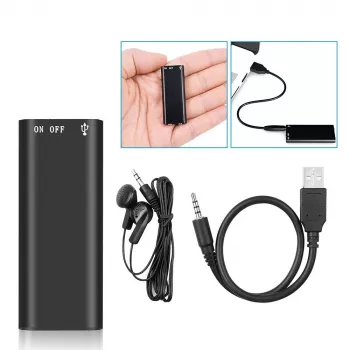
- Record quick decisions: If you tend to forget what you agreed on, a simple recorder can capture the action items. The Mini 8GB Voice Recorder Digital Audio MP3 Player USB Pen with Earphones is an easy way to keep notes without derailing the meeting.
- Use one “money hub”: Keep the bill calendar, sinking funds, and goal tracker together so the plan isn’t scattered across apps and paper.
Include Kids Without Turning Money Into Anxiety
Use a Digital Planner to Keep Everything in One Place
What to Look for in a Family Budget Planner
| Feature | Why It Helps | Best For |
|---|---|---|
| Monthly budget pages | Sets the plan before the month starts | Households with steady income |
| Weekly check-in pages | Catches overspending early | Busy families with variable schedules |
| Goal trackers | Creates motivation and visibility | Saving for trips, emergencies, or big purchases |
| Bill calendar | Reduces late fees and missed payments | Multiple due dates across the month |
Common Roadblocks and Quick Fixes
Troubleshooting Guide
| Problem | What Usually Causes It | One Change to Try This Week |
|---|---|---|
| Budget never matches reality | Missing sinking funds | Add 1 sinking fund and set a small monthly amount |
| Arguments about spending | No agreed boundaries | Create equal personal allowances |
| Goals stall | Savings not automated | Schedule an automatic transfer on payday |
| Late fees | Due dates spread out | Add a bill calendar and reminders |
FAQ
How often should a family review the budget?
Aim for a weekly or biweekly check-in that stays under 20 minutes, plus a monthly planning session to set categories and due dates. Consistency matters more than length.
What’s the easiest way for families to start saving money together?
Pick one shared goal (like a $500 starter emergency fund), automate a small transfer right after payday, and track progress visually where everyone can see it. Keep the first budget categories simple and expand later.
How can families budget with irregular income?
Use a conservative baseline income, cover essentials first, and fund sinking funds to smooth out uneven months. Decide ahead of time where “extra” income goes (catch up bills, savings, debt, then fun) so it doesn’t disappear.


Leave a comment